NZ Insurance Regulations: What Business Owners Actually Need to Know
Most business owners buy insurance and file it away. They don't think about the regulatory framework sitting behind that policy, until something goes wrong.
But NZ insurance regulations aren't just bureaucratic background noise. They directly affect whether your claim gets paid, whether your broker is working for you or the insurer, and whether your policy is even enforceable. This article breaks down what you actually need to understand.
Years of experience
Clients protected
5-star reviews
Why the Regulatory Framework Actually Matters to You
Insurance regulations aren't something most business owners spend much time thinking about. You've got a policy, you pay the premium, you assume you're covered. That's the deal, right?
Not quite.
The legal and regulatory framework governing business insurance in New Zealand has real teeth. It shapes what your broker can and can't do, what your insurer is required to tell you, and, critically, what happens when you make a claim. Understanding the basics isn't just useful. It can be the difference between a paid claim and a declined one.
The Regulatory Landscape in NZ
Business insurance in New Zealand sits within a framework built primarily around two pieces of legislation: the Financial Markets Conduct Act 2013 (FMCA) and the Financial Advisers Act 2008. Together, these laws govern who can give financial advice, how that advice must be delivered, and what standards apply.
The Financial Markets Authority (FMA) is the regulator responsible for overseeing financial advice in New Zealand. If someone is giving you advice about insurance, whether that's recommending a policy, helping you structure your cover, or guiding you through a claim, they need to be operating under a Licensed Financial Advice Provider (FAP).
Gerrards holds FAP status. That's not just a credential on a wall. It means we're legally required to act in your interest, maintain competency standards, and give advice that's appropriate to your situation. A direct insurer selling you their own policy doesn't operate under the same obligation. They're selling a product. We're giving advice.
The Financial Services Council (FSC) also plays a role in the broader industry, setting standards and advocating for a well-functioning financial services sector in New Zealand. While the FSC isn't a regulator in the same sense as the FMA, its code of conduct and member standards contribute to the expectations placed on insurers and advisers alike.
What the Law Requires of Your Broker
Under the FMCA, financial advisers, including insurance brokers, must meet what's called the "client care" obligation. In plain terms, this means:
- Advice must be suitable for your specific circumstances
- Conflicts of interest must be disclosed
- Fees and commissions must be transparent
- You must be told if the adviser has a limitation on the advice they can give
Here's what that means in practice. When Gerrards recommends a policy, we're required to explain why it suits your situation, not just quote a number and move on. We have access to 20+ insurers, which means we can genuinely compare the market rather than defaulting to whoever pays the highest commission.
And at claim time? We're legally and ethically required to advocate for you. Not the insurer. That distinction matters enormously when a claim is disputed.
Your Obligations as the Insured
Regulation doesn't just apply to brokers and insurers. You have legal obligations too, and not knowing about them doesn't protect you from the consequences.
Duty of Disclosure
When you apply for insurance, you're required to give true and accurate information. This isn't just a courtesy. Policy wordings from the insurers we work with are explicit: false or incomplete information at application can make a policy unenforceable.
But it doesn't stop at application. If your circumstances change materially, you take on a new type of work, your turnover increases significantly, you hire more staff, you move premises, you're required to tell your insurer. A "material" change is defined as anything that would have affected the insurer's decision to offer cover, or the terms they'd have offered.
If you don't notify them and something goes wrong, the insurer may decline your claim from the date you knew about the change. Not from the date you reported it. From the date you knew.
This is one of the most common ways business owners end up underinsured or uninsured without realising it.
Reasonable Care
Policy conditions typically require you to take reasonable care to avoid circumstances that could give rise to a claim. Reckless or grossly irresponsible behaviour can void your cover. That's a legal standard, not just insurer preference.
Don't Admit Liability
This one catches people out. If something happens, a customer slips, a contractor damages property, a product causes harm, your instinct might be to apologise or acknowledge fault. Don't. Most liability policies include a condition that you must not admit liability or say anything that could prejudice the insurer's ability to defend a claim on your behalf. Admitting fault, even informally, can compromise your position significantly.
If you're ever unsure what to say after an incident, call your broker first.
The Fair Insurance Code
Beyond legislation, New Zealand insurers who are members of Insurance Council NZ operate under the Fair Insurance Code. This sets minimum standards for how insurers must handle claims, communicate with policyholders, and resolve disputes.
It's not a substitute for reading your policy. But it does mean you have recourse if an insurer handles your claim poorly. If you believe an insurer has acted unfairly, you can escalate through the Insurance and Financial Services Ombudsman (IFSO) scheme, a free dispute resolution service available to policyholders.
At Gerrards, we help clients navigate this process. Having a broker in your corner when a claim is disputed isn't just useful, it's often the reason a claim gets resolved in your favour rather than the insurer's.
What This Means When You're Buying Insurance
Understanding the regulatory framework changes how you should approach buying business insurance.
First, make sure whoever is advising you is actually authorised to do so. Ask whether they're operating under a FAP licence. If they can't answer that clearly, that's a problem.
Second, treat your disclosure obligations seriously. When you're filling out a proposal form, answer every question accurately. If you're unsure whether something is relevant, disclose it anyway. The policy wordings we work with are clear on this: if in doubt, notify. The cost of over-disclosing is negligible. The cost of under-disclosing can be your entire claim.
Third, review your policy every year. Not just the premium, the actual terms. Your business changes. Your risk profile changes. A policy that was right two years ago might have gaps today. At Gerrards, we audit every client's policy annually for exactly this reason. We've seen too many businesses discover coverage gaps only after filing a claim.
Why an Independent Broker Changes the Equation
Direct insurers can't advocate for you at claim time. It's a structural conflict of interest, they're the ones deciding whether to pay. A broker who is legally required to act in your interest, and who has access to the full market rather than a single product suite, is a fundamentally different proposition.
That's not a sales pitch. It's the regulatory reality.
When a claim is disputed, when policy wording is ambiguous, when an insurer is slow to respond, having someone in your corner who knows the rules, knows the insurers, and is legally obligated to fight for your outcome makes a real difference.
What to Do Next
If you haven't reviewed your business insurance recently, or if you're not certain your broker is operating under a FAP licence, it's worth a conversation.
Gerrards works with businesses across New Zealand, across industries, and across risk profiles. We compare options from 20+ insurers, we explain what the policy actually says, and we're there when you need to make a claim.
This is general information only. For advice tailored to your specific situation, get in touch with our team.
We're available 8am-7pm, seven days a week. Same-day quotes. No runaround.
Meet the author
See the author who wrote this article
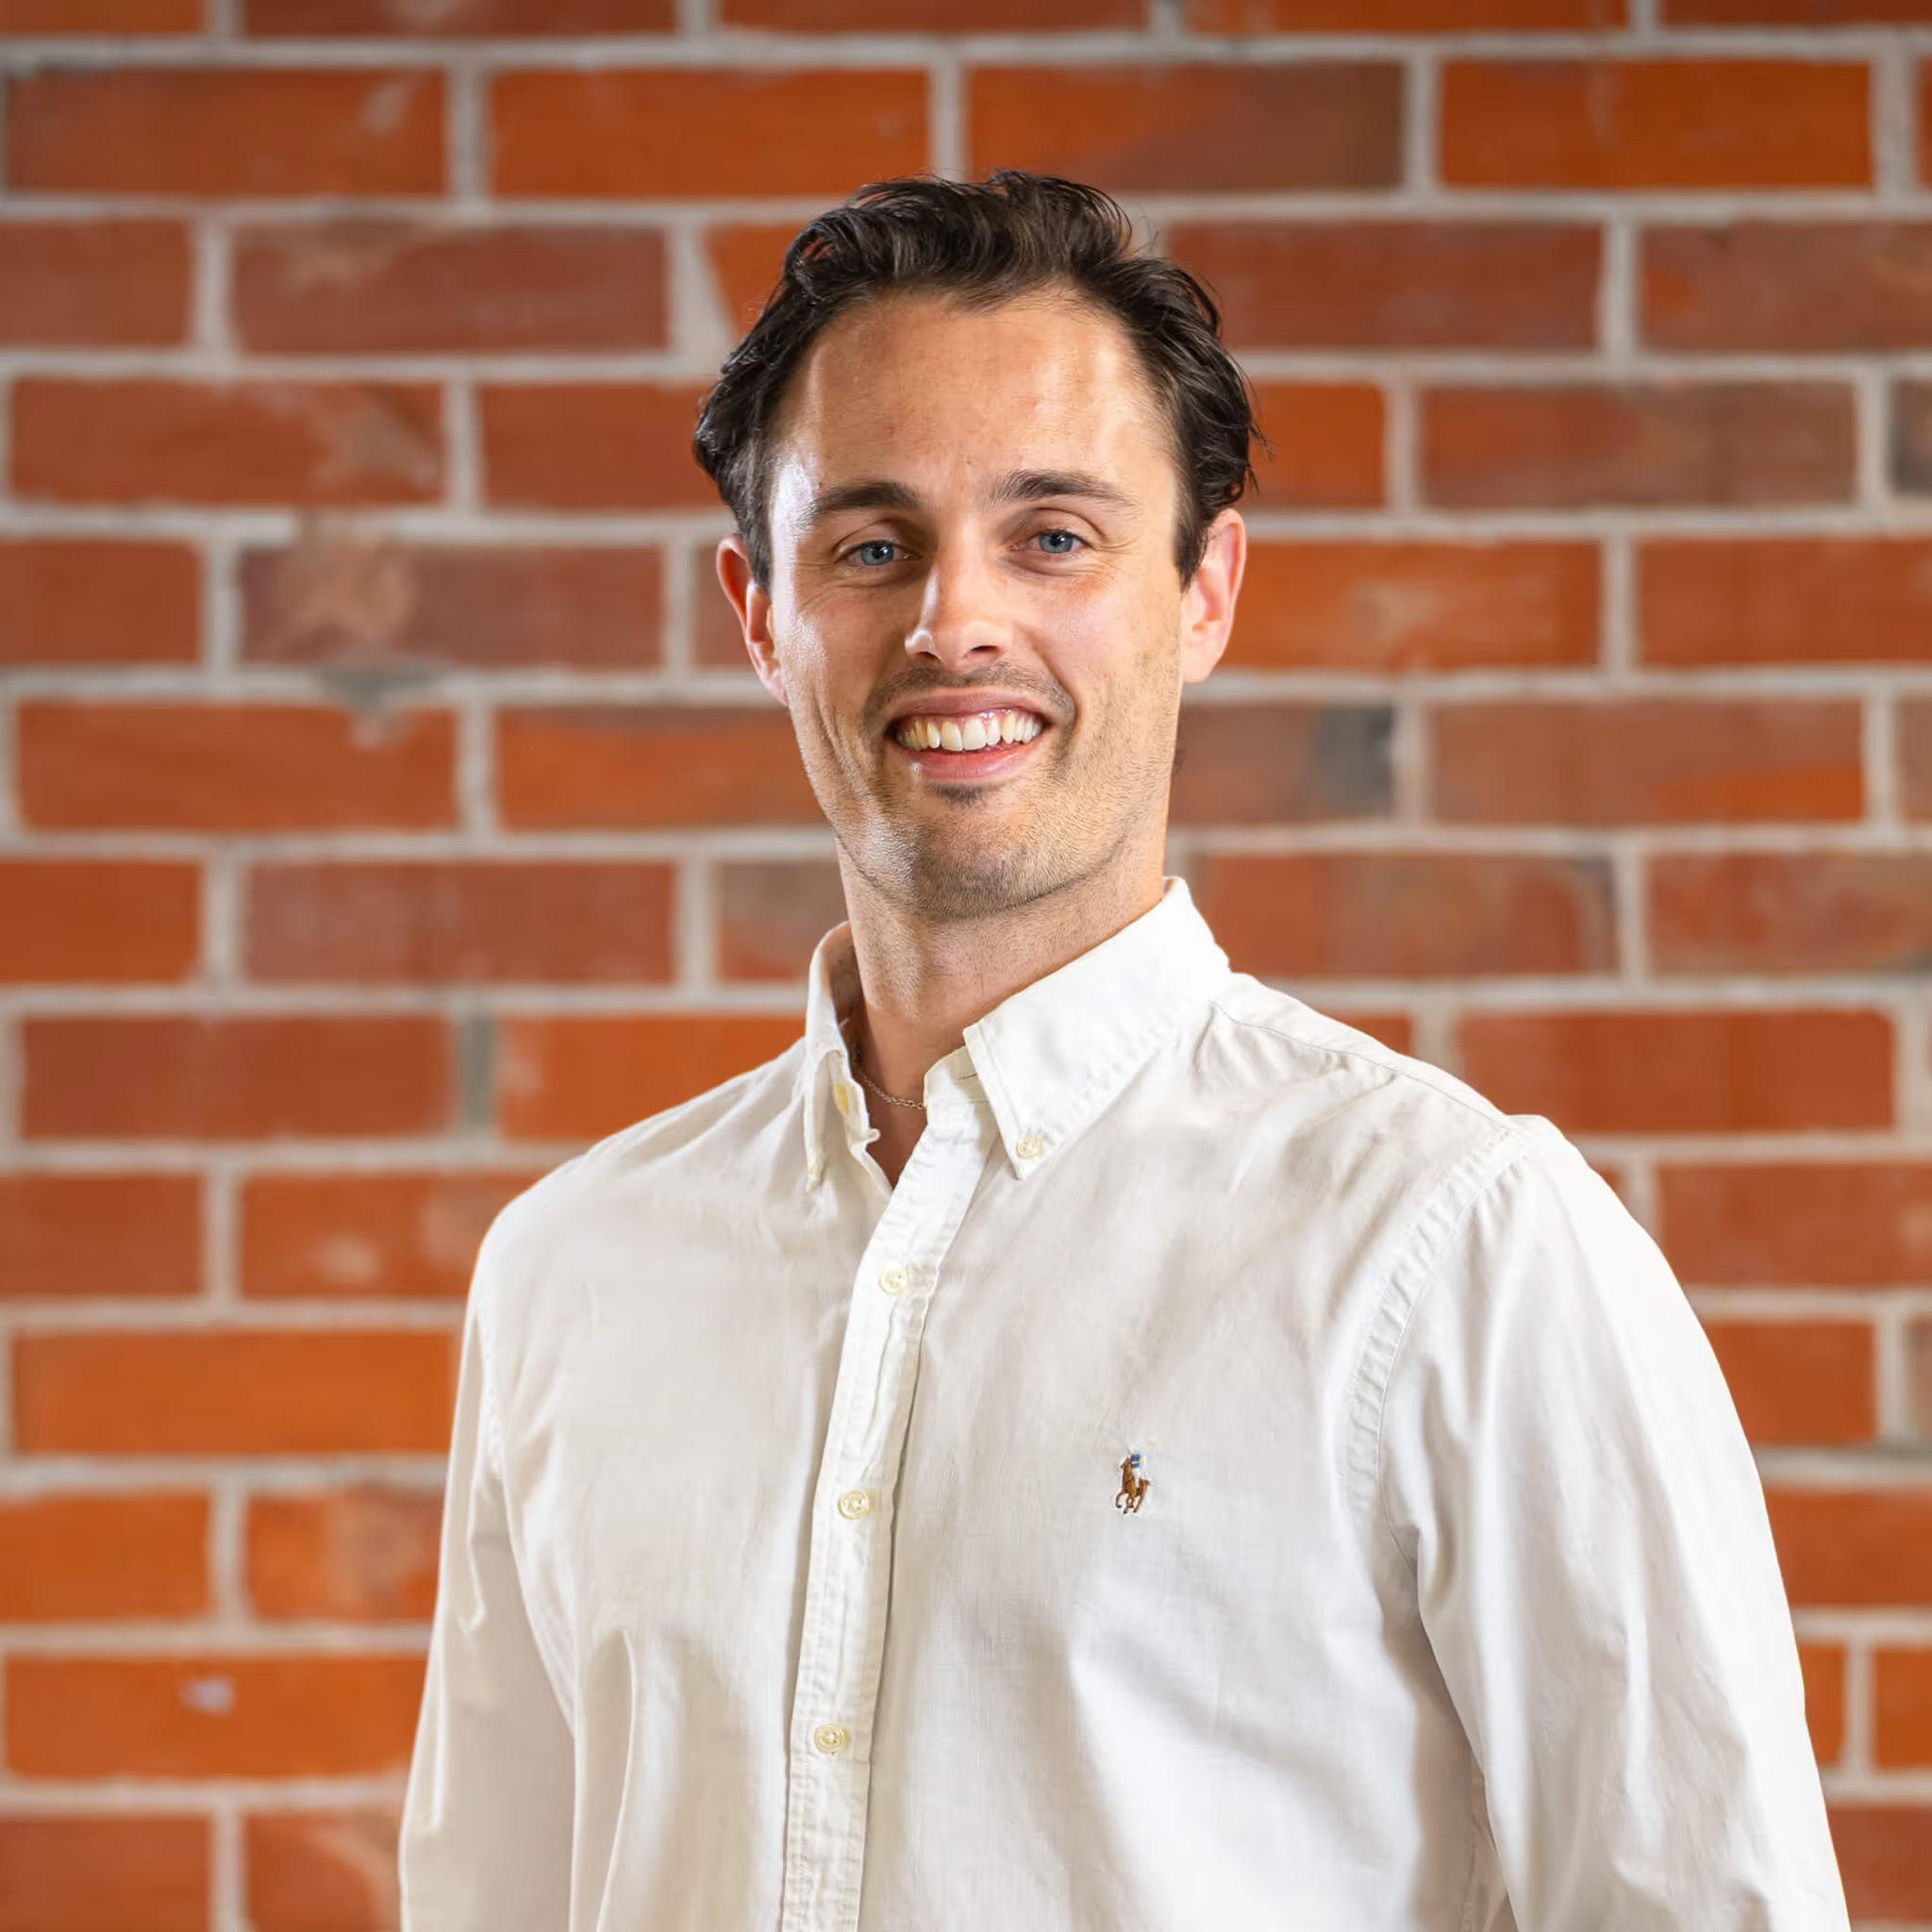
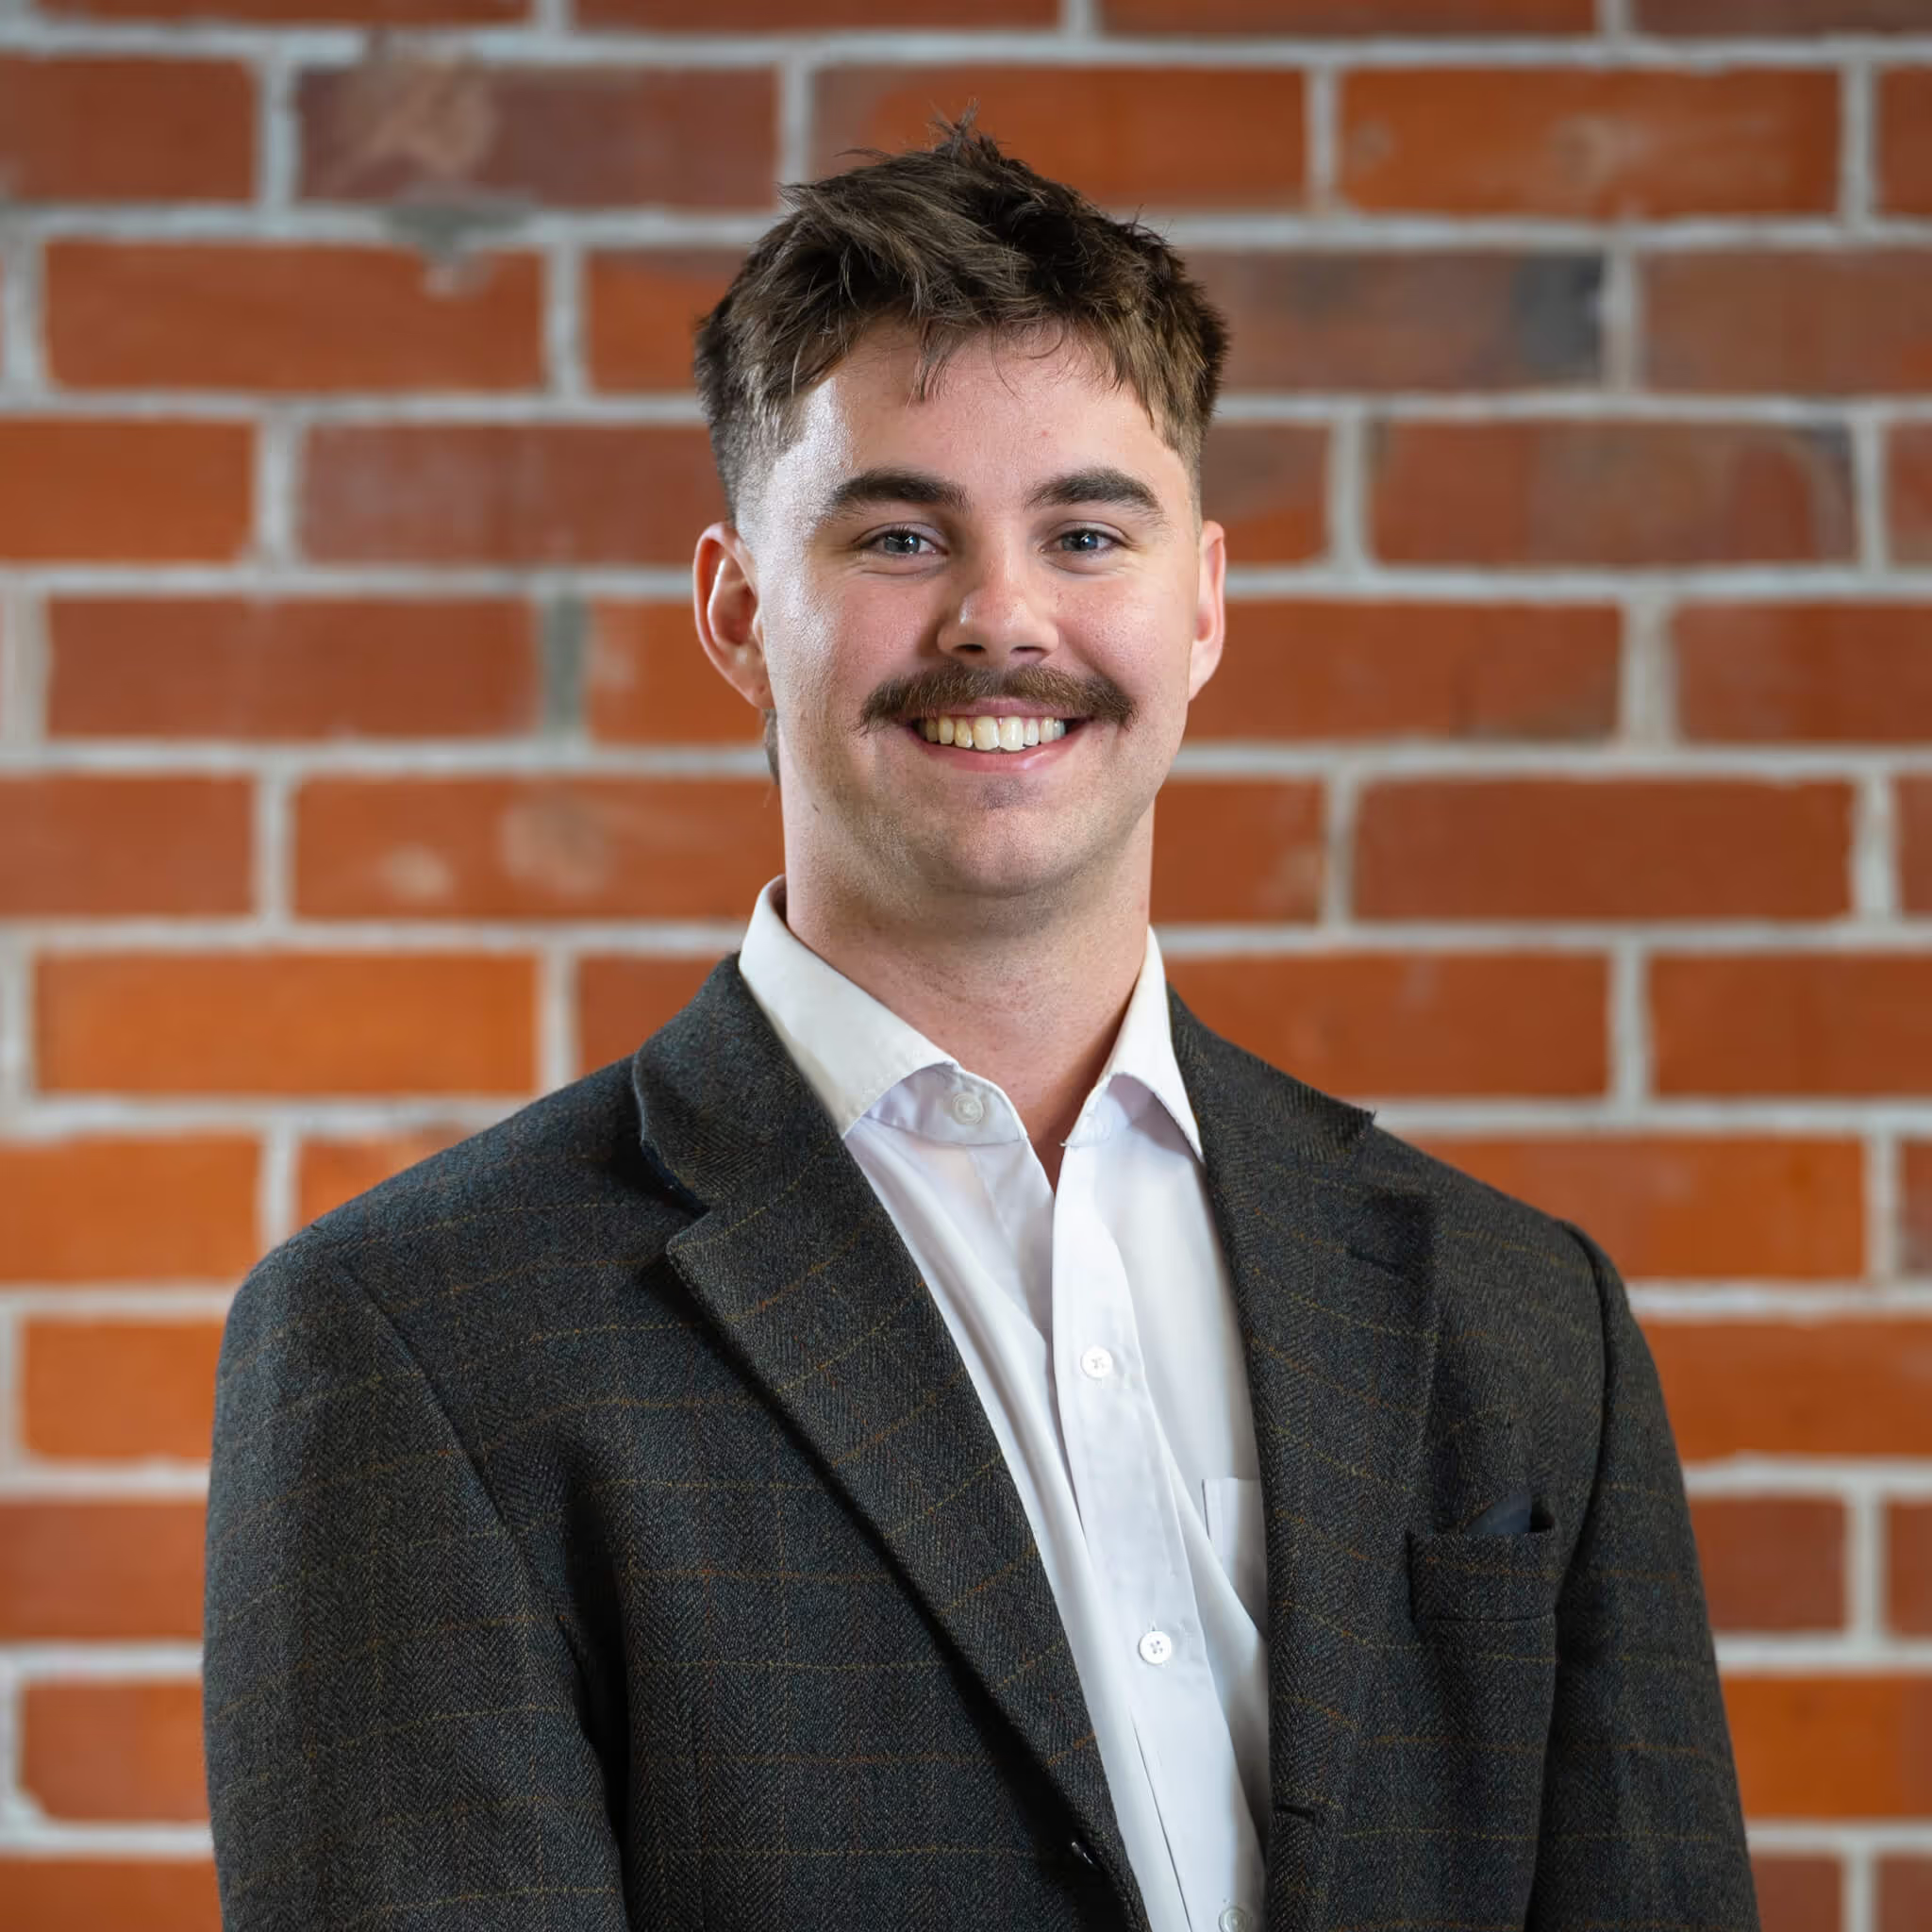
Reuben Elkins is a Commercial Insurance Broker at Gerrard's based in Christchurch, New Zealand, with a background in insurance system processing and a strong focus on commercial client risk placement.




Secure the exact cover your business needs
Getting insured shouldn't be a headache. We use innovative technology to strip away the paperwork and deliver a tailored, accurate quote in record time.