Business Insurance for Startups in New Zealand: What Cover Do You Actually Need?
Starting a business in New Zealand is exciting. Insurance? Not so much. But getting your cover wrong from day one is one of the most expensive mistakes a new business owner can make, and it happens constantly.
This isn't about buying every policy on the shelf. It's about understanding which risks are real for your business, which ones could sink you, and how to make sure you're not paying for cover you don't need while leaving yourself exposed where it actually counts.
Years of experience
Clients protected
5-star reviews
Most startups get their insurance backwards
Here's what usually happens. A new business owner signs up for whatever policy comes up first in a Google search, or ticks the box their accountant mentioned, or just copies what their last employer seemed to have. They pay the premium, file the certificate somewhere, and move on.
Then something goes wrong.
Maybe a client claims your advice caused them a financial loss. Maybe a contractor trips on your job site. Maybe your tools get stolen out of your van on a Tuesday morning. And that's when the policy gets read properly, usually for the first time.
Getting business insurance right as a startup in New Zealand isn't complicated. But it does require thinking about your actual risks, not just ticking boxes.
Why the stakes are higher when you're new
Established businesses have cash reserves, relationships, and sometimes the ability to absorb a bad month. Startups usually don't.
A single uninsured liability claim can wipe out a new business before it's had a chance to find its feet. A gap in your professional indemnity cover can turn a client dispute into a legal bill you can't pay. And if your key equipment is damaged or stolen without the right cover in place, you might not have the capital to replace it quickly enough to keep operating.
The risk isn't just financial. It's existential.
That's not meant to scare you. It's just the reality of why getting this right early matters more than most people realise.
The cover most NZ startups actually need
Public liability insurance
This is usually where you start. Public liability covers you if your business causes injury to someone or damages their property. It's relevant the moment you have any interaction with clients, suppliers, or members of the public, which is basically every business.
Say you're a new landscaping company and a client trips over your equipment on their property. Or you're a startup retailer and a customer slips in your store. Or you're a tradie and you accidentally damage a client's home while working on it. Public liability is what stands between you and a claim that could cost tens of thousands of dollars.
For many industries, construction, trades, hospitality, events, clients and contractors will require proof of public liability before they'll work with you at all. It's not optional.
Professional indemnity insurance
If your business involves giving advice, providing designs, writing reports, or delivering any kind of professional service, professional indemnity cover belongs on your list.
This policy responds when a client claims that your work, or your error, omission, or negligent advice, caused them a financial loss. It covers your legal defence costs and any damages you're found liable for, up to the policy limit.
Consultants, architects, engineers, accountants, IT professionals, marketers, lawyers, if you charge for your expertise, you're exposed. And the thing about professional indemnity claims is that they often arrive long after the work was done. A design error on a building project might not surface for two years. A piece of financial advice might be challenged 18 months later.
Keep in mind that professional indemnity policies are typically written on a "claims made" basis, meaning the policy in force when the claim is made is what responds, not the policy in force when the work was done. That's worth understanding before you let a policy lapse.
Business assets and equipment cover
If your business owns physical assets, tools, equipment, stock, fit-out, computers, vehicles, you need to think about what happens if they're damaged, destroyed, or stolen.
For a new construction company, this might mean plant and machinery, power tools, and materials on site. For a tech startup, it might be servers and laptops. For a café, it's your commercial kitchen equipment.
The key thing to get right here is your sum insured. Underinsuring your assets is one of the most common mistakes we see. If you insure $50,000 worth of equipment for $20,000 because the premium is lower, you'll find out why that was a bad idea when you make a claim.
Make sure your sum insured reflects what it would actually cost to replace everything at today's prices, not what you paid for it two years ago.
Business interruption insurance
This one gets overlooked constantly, especially by startups who assume it's only for big companies.
Business interruption cover kicks in when an insured event, a fire, a flood, a major equipment failure, stops you from trading. It replaces lost revenue and covers ongoing fixed costs like rent and wages while you get back on your feet.
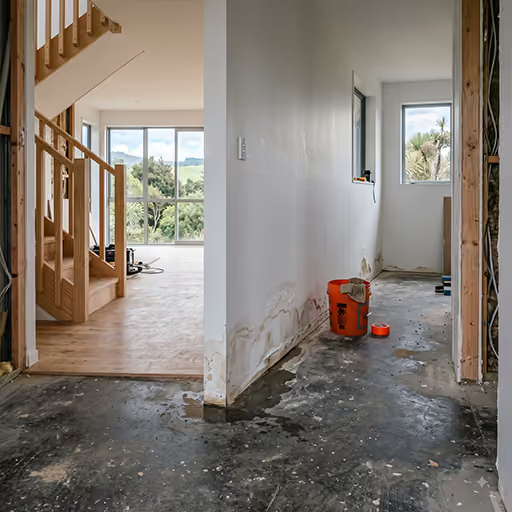
Imagine your workshop burns down. Your material damage policy covers the rebuild. But who pays your rent for the six months it takes to get back up and running? Who covers your staff wages? Who replaces the revenue you're not earning?
Without business interruption cover, you're paying those costs out of your own pocket, assuming you have the reserves to do it at all.
Employers liability and ACC top-up
If you have staff, this matters. ACC covers workplace injuries in New Zealand, but it doesn't cover everything. Employers liability insurance fills gaps that ACC leaves, particularly around claims that fall outside the ACC scheme.
As your team grows, this becomes more important. But even with one or two employees, it's worth understanding what you're exposed to.
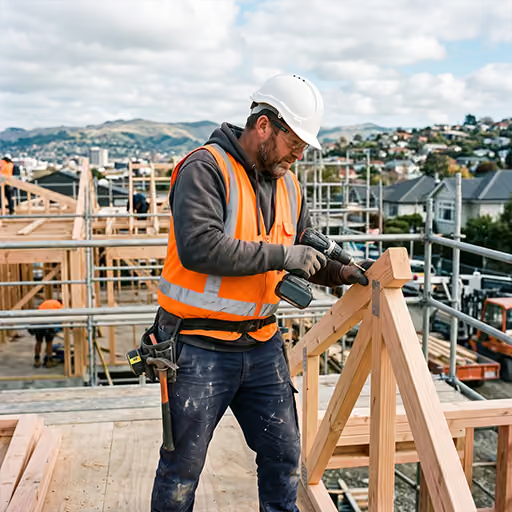
What new construction companies need to think about specifically
Construction is one of the higher-risk categories for startups, and the insurance requirements reflect that.
Beyond public liability, a new construction business typically needs to think about:
Contract works insurance, covers work in progress on a construction site against damage, theft, or loss before the project is complete and handed over. If a storm damages a half-built structure, contract works cover is what responds.
Tools and plant cover, construction equipment is expensive and frequently targeted. A comprehensive tools policy covers your gear on site, in transit, and stored overnight.
Statutory liability, covers fines and legal costs arising from unintentional breaches of New Zealand statutes, including the Health and Safety at Work Act 2015. For construction companies, this is genuinely important.
Motor vehicle cover, if you're running utes, trucks, or any vehicles for the business, commercial motor vehicle insurance is separate from your personal car policy and needs to be arranged properly.
The policy wordings that govern these covers contain specific definitions, what counts as a "vehicle," what qualifies as "mechanical plant," how liability defence works, who controls settlement decisions. These aren't small details. They determine what actually happens when you make a claim.
The gap between what you think you're covered for and what you actually are
This is where most problems start.
Insurance policies are legal contracts. What matters is what's written in the policy schedule and the policy wording, not what a website summary says, not what you assumed, and not what the person on the phone implied when you bought it.
Liability policies, for example, contain specific provisions around how claims are defended, who controls the defence, and under what circumstances a settlement can be made. Some policies give the insurer the right to appoint their own lawyers and settle claims as they see fit. Others have more collaborative processes. Understanding this before you need it is far better than discovering it during a claim.
The same applies to exclusions. Many standard liability policies exclude certain industries, certain activities, or certain types of work. A construction company doing occasional agricultural contracting, for instance, might find that work sits in a grey area depending on how the policy defines it.
What we see at Gerrards is that startups often buy policies without reading them, and sometimes without anyone explaining what they actually cover. That's not a criticism. It's just what happens when you're busy building a business and insurance feels like a compliance exercise rather than a genuine risk management decision.
How to actually get this right
Start by mapping your real risks. Not the risks you think sound serious, the ones that could actually stop your business from operating or expose you to a claim you can't pay.
Ask yourself:
- What happens if I injure a client or damage their property?
- What happens if a client claims my work caused them a financial loss?
- What happens if my key equipment is stolen or destroyed?
- What happens if I can't trade for three months?
- Do I have staff, and what are my obligations to them?
Once you've thought through those scenarios honestly, you have a much clearer picture of where your exposure actually sits.
Then get proper advice. Not a comparison website, those give you quotes, not advice. Not a direct insurer, they can only offer their own policies, and at claim time, they're working for themselves, not for you.
An independent broker has access to multiple insurers and can genuinely compare what's available across the market. More importantly, when something goes wrong, a broker advocates for you, not for the insurer. That distinction matters enormously when you're in the middle of a claim and the insurer is looking for reasons to limit their payout.
At Gerrards, we work with 20+ insurers and we review policies annually, because the right cover for a startup in year one isn't always the right cover in year three, and premiums and policy terms shift constantly.
Don't wait until something goes wrong
The businesses that get insurance right from the start aren't the ones that worry about it the most. They're the ones that took an hour early on to understand their actual risks, got the right cover in place, and then got back to building their business.
Every business is different. Your policy needs will depend on your industry, your clients, your assets, and how you operate. This is general information only, for advice tailored to your specific situation, get in touch with our team.
We're available 8am to 7pm, seven days a week, and we can usually turn around a quote the same day.
Meet the author
See the author who wrote this article
Insurance Broker at Gerrard's with a background spanning sales, claims, branch advisory, and underwriting roles across AMI, IAG, and NZI. Committee member of Young Insurance Professionals (YIPs). Based in Christchurch, New Zealand.




Secure the exact cover your business needs
Getting insured shouldn't be a headache. We use innovative technology to strip away the paperwork and deliver a tailored, accurate quote in record time.